
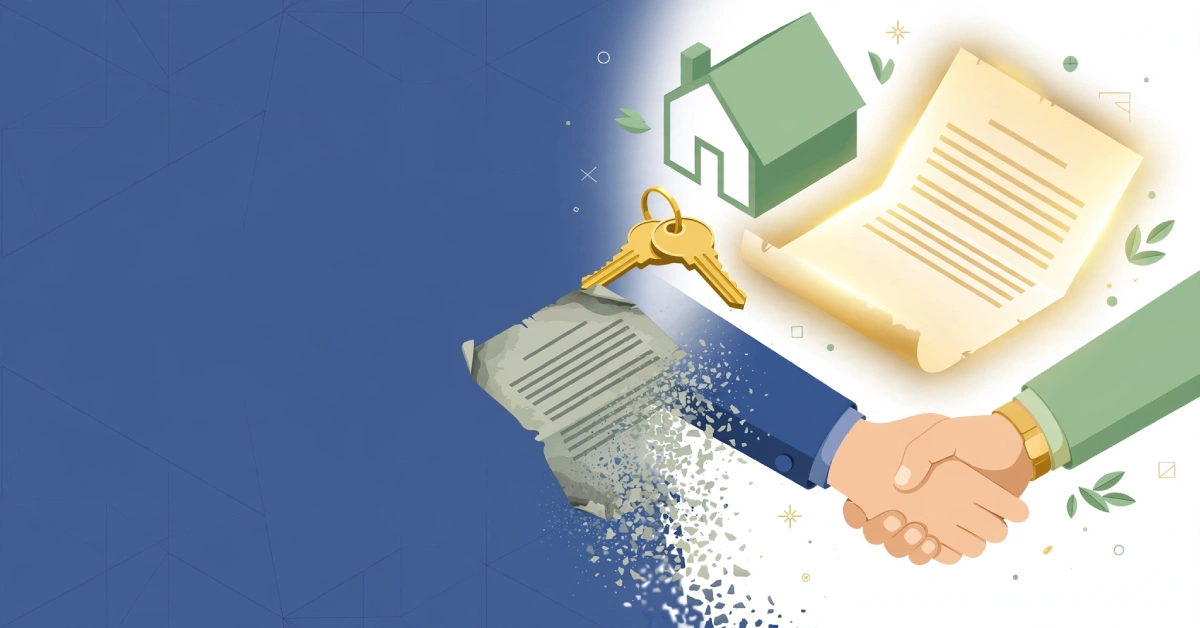
Novation in real estate is a legal process that completely replaces an existing contract with a new one, transferring all rights and obligations to different parties or under new terms. Unlike contract assignments that only transfer some rights while keeping the original party liable, novation requires consent from all parties and fully releases the original party from its contractual duties.
This tool helps investors, buyers, and sellers renegotiate deals, transfer property obligations, and adapt to changing market conditions without starting the entire transaction process over.
What Novation Means in Real Estate Deals
Novation creates a brand new contract that nullifies the original agreement. You can change who’s involved, what terms apply, or both. The key difference from other contract changes is that everyone walks away from the old contract entirely.
This is different from an amendment or modification, which changes specific terms while keeping the original contract intact. Novation requires universal consent—every party must agree to the new agreement. It also results in a release of liability for the original party, meaning they are no longer bound by the old contract. You can perform a party substitution (replacing a buyer or seller) or a term substitution (changing price, dates, etc.), or both. While novation is more common in commercial real estate, it can be used in residential contracts as well, including rental agreements.
Think of it like replacing a car part. You don’t just patch the old one. You remove it completely and install a fresh replacement.
The process needs three things to work: an existing valid contract, mutual agreement from everyone involved, and a written document that outlines the new terms. Verbal agreements don’t count.
How Investors Use Novation Real Estate Strategies
Real estate investors turn to novation when they want to control property deals without taking title. You secure a property under contract, find an end buyer, and then transfer your position through novation.
Here’s how it typically flows. An investor signs a purchase agreement with a seller. Before closing, they locate another buyer willing to take over. The investor and seller execute a novation agreement that removes the investor and inserts the new buyer. The new buyer closes on the property while the investor collects a fee.
Instead of assigning your rights or using a double closing, novation allows you to substitute the buyer directly. This approach works well when you need to market properties to retail buyers who want traditional financing. Lenders and title companies often prefer novation over assignments because the paperwork is cleaner and the original investor is completely out of the picture. However, this also means the deal is subject to underwriting, appraisals, inspections, and lender approval.
You can also list properties on the Multiple Listing Service using novation agreements. This opens your deals to a wider buyer pool, including families looking for primary residences who might pay closer to market value. If you plan to list on the MLS, consider using a flat-fee broker to ensure you’re not engaging in unlicensed brokerage activity.
Three Types of Novation You Need to Know
Standard Novation
Two parties agree to change the terms of their existing contract. The seller might agree to lower the purchase price after an inspection reveals foundation issues. Both sign off on the new price, and the old contract becomes void.
Three-Party Novation
This involves the transferor, transferee, and counterparty. All three must agree to the new terms. A common example is when a buyer wants to transfer mortgage responsibility to another party. The seller, new buyer, and lender all need to approve the change.
If one party objects, you can’t move forward with the current terms. Everyone needs to negotiate until all parties agree.
Delegation Novation
The original party transfers all contractual duties and benefits to a new party. The new party assumes full responsibility while the original party is released from all obligations.
Novation vs Assignment: Key Differences That Matter
Novation and assignment both transfer contract interests, but they work differently in important ways.
With an assignment, you transfer your rights to another party, but you stay on the hook if things go wrong. If your assignee defaults, you’re still responsible to the seller. The original party often remains secondarily or primarily liable. Novation cuts you loose completely. Once all parties sign the novation agreement, you have zero liability. The new buyer and seller are the only parties to the contract.
An assignment typically doesn’t need the seller’s consent if your original contract allows assignments. Novation always requires seller approval.
The original contract stays valid with the assignment. Novation replaces it entirely. Also, unlike a simple amendment that modifies specific terms, novation replaces the entire contract. Some investors consider joint ventures (JVing) as another alternative, but novation is unique in its complete substitution.
For wholesaling off-market deals, assignment often makes more sense. For marketing properties through the MLS or to retail buyers, novation is usually the better choice.
Contract Elements You Can Change Through Novation
- Purchase price adjustments
- Earnest money deposit amounts
- Closing date modifications
- Buyer or seller name changes
- Repair credit negotiations
- Lease term updates
- Rent payment schedules
- Security deposit requirements
- Property condition clauses
- Financing contingencies
- Move-in/move-out dates
When Novation Makes Sense for Your Deal
Use novation when you need seller cooperation and want clean title work. It’s particularly useful in these situations.
You’re marketing properties to buyers who need conventional, FHA, or VA financing. These buyers and their lenders want straightforward contracts without assignment language.
The property needs minor repairs before you can sell at full market value. You handle the repairs between contract signing and closing, delivering better value to both seller and buyer.
Your seller is hesitant about wholesale assignments. Novation feels more professional and creates less confusion for sellers unfamiliar with investor strategies.
You want to list on the MLS to attract the largest buyer pool. Novation agreements are more acceptable to listing services and real estate agents.
Benefits of Using Novation Agreements
You eliminate personal liability once the novation executes. This protects you from any issues that arise between the new buyer and seller. This can also protect a business’s reputation and credit compared to cancelling a contract or defaulting on a loan.
Sellers often prefer novation because they may avoid standard real estate commissions. They still get wider market exposure through MLS listings. However, note that sellers may still owe commissions if they have an existing listing agreement.
You can generate profits without taking title to the property. This reduces your holding costs, financing needs, and tax complications.
The transaction looks cleaner to lenders and title companies. This can speed up closing times and reduce the chance of funding issues.
You open your deals to retail buyers who represent a larger market. This competition can drive up your novation fee compared to selling only to other investors.
Risks and Challenges to Watch For
Novation requires seller buy-in. If your seller refuses to sign, you can’t move forward. This makes relationship building and clear communication critical.
The legal complexity is higher than in simple assignments. You need properly drafted agreements to ensure all obligations transfer correctly and protect all parties.
Closing timelines may extend when retail buyers use traditional financing. Loan approvals take time, which can frustrate sellers expecting quick cash closes. Appraisals can come in low and blow the deal. Lenders may question your fee or raise red flags.
If your end buyer’s financing falls through, the deal collapses. Unlike an assignment, where you might still have backup options, novation typically means starting over.
Market conditions can shift during the extended timeline. A property that seemed like a good deal initially might not work if values drop before closing. Retail buyers often require walkthroughs and may ask for concessions, which can reduce your profit.
Also, novation is not a no-money strategy; it’s a low-capital strategy at best. You may need to cover option deposits, appraisal fees, repairs, MLS access, cleaning, staging, transaction coordination, and legal review—costs that can total $1,500 to $5,000 or more before you get paid.
Legal Requirements for Valid Novation
Your novation agreement needs explicit language releasing the original party from liability. Vague wording creates future disputes.
All parties must provide written consent. This includes the original buyer, seller, and new buyer. Email confirmations don’t count as proper documentation.
The agreement should detail who pays what fees. Your novation fee structure needs to be clear, along with which party handles title insurance, inspections, and closing costs.
Work with a title company experienced in novation transactions. They’ll ensure your agreement complies with local real estate laws and lender requirements.
Conduct a title search before finalising the novation. Unknown liens or encumbrances can kill deals after you’ve invested time and money.
If the property has existing financing, you may need lender approval. Not all mortgages allow transfer through novation, particularly those with due-on-sale clauses.
Novation is governed by state contract law, and requirements vary. Courts have ruled that some novation deals lack proper disclosures or create unlicensed agency. Failing to disclose novation to the seller could be a breach of contract or even fraud. Some states consider certain novation activities as unlicensed brokerage activity. Therefore, transparency and full disclosures are essential. Also, if there’s an inspection contingency, it may give buyers leverage to renegotiate.
How to Structure Your Novation Fee
Most investors collect between 3% and 10% of the purchase price as a novation fee. The exact amount depends on your market, property condition, and how much work you put into the deal.
Some investors charge flat fees instead of percentages. This works well for lower-priced properties where percentage-based fees might not justify your time.
Your fee typically gets paid at closing from the seller’s proceeds. Make sure your novation agreement specifies this payment structure clearly.
The seller’s closing costs and any real estate commissions usually come out of the total before you receive your fee. Factor this into your calculations when evaluating deals.
Build your fee structure into the initial contract terms. This prevents surprises and ensures everyone understands the financial arrangement upfront.
Your fee should be clearly disclosed on the HUD or settlement statement. Lenders may question your fee, so be prepared to justify it with a clean paper trail and a signed agreement. Unusual fees can raise red flags and cause the deal to fall apart.
Common Novation Scenarios in Real Estate
Mortgage Assumption Transfers
A seller with an existing mortgage finds a buyer willing to assume the loan. All three parties execute a novation that transfers the debt obligation to the new buyer while releasing the seller.
Lease Assignment in Commercial Properties
A business tenant wants to exit a long-term lease early. They find a new tenant acceptable to the landlord. The novation transfers all lease obligations to the replacement tenant.
Partnership Interest Changes
Real estate partnerships sometimes need to replace members. Novation allows the incoming partner to assume all rights and duties of the exiting partner.
Inspection-Based Price Adjustments
Post-inspection negotiations reveal $15,000 in needed repairs. Rather than credit the buyer or make repairs, the parties execute a novation, lowering the purchase price by that amount.
Replacing an Individual with an LLC
An investor who originally signed a contract as an individual can use novation to substitute a newly formed entity like an LLC. All parties must agree, and the lender may need to approve if financing is involved.
Best Practices for Successful Novation Deals
Start with a solid initial contract. Make sure your original purchase agreement allows for novation or, at a minimum, doesn’t prohibit it.
Build relationships with sellers before mentioning novation. Take time to understand their goals and concerns. Position novation as the solution to their specific situation.
Have your novation agreement template ready before you need it. Work with a real estate attorney to create a form that works in your state and protects your interests.
Communicate constantly with all parties. Keep the seller updated on your marketing progress. Keep the buyer informed about inspection results and closing timelines.
Set realistic expectations about closing timelines. Don’t promise 30-day closes if you’re marketing to retail buyers who need financing.
Screen end buyers carefully. Verify their financing pre-approval and ability to close before executing the novation agreement.
Maintain a clean paper trail for all transactions. Work with retail buyers and their agents professionally. If you plan to list on the MLS, use a flat-fee broker to stay compliant. Transparency is non-negotiable—disclose everything to everyone.
Tax Implications of Novation Transactions
Your novation fee is taxable income. The IRS treats it as ordinary income, not capital gains, since you never took title to the property.
Keep detailed records of all expenses related to the transaction. Marketing costs, inspection fees, and legal fees may be deductible against your novation income.
Consult with a tax professional about your specific situation. Tax treatment can vary based on your business structure and whether you’re conducting novation as a business or occasional activity.
Some investors form LLCs or S corporations to handle novation deals. This can provide liability protection and potentially better tax treatment.
Finding Properties for Novation Deals
Direct mail campaigns to motivated sellers work well. Look for properties that need minor cosmetic work but have solid bones.
Networking with real estate agents can uncover pocket listings. Some agents have sellers willing to try creative solutions before hitting the public market.
Driving for dollars in transitional neighbourhoods reveals properties where owners might welcome a hands-off sale solution.
Online marketing through Facebook, Google Ads, and real estate websites generates seller leads interested in quick, simple transactions.
Probate and divorce situations often create motivated sellers open to novation arrangements that reduce their involvement in the sale process.
Use comps to estimate the after-repair value (ARV) and ensure the deal works. Look for properties where the ARV supports a profitable novation fee.
Working with Title Companies on Novation
Choose a title company familiar with investor transactions. Not all title companies understand or accept novation agreements.
Provide your novation agreement early in the process. This gives the title company time to review and request any needed modifications.
Explain the fee structure clearly. Make sure the title company understands how and when your novation fee gets paid from closing proceeds.
Ask about their specific documentation requirements. Some title companies need additional affidavits or disclosures for novation transactions.
Build long-term relationships with investor-friendly title companies. Having a trusted partner makes future deals much smoother.
Final Thoughts
Novation real estate strategies give you the flexibility to structure deals that work for everyone involved. You can generate income without taking title, sellers avoid agent commissions while still getting market exposure, and buyers get properties they might not find through traditional channels.
Success requires understanding the legal requirements, building strong relationships with sellers and title companies, and properly screening end buyers. The extra complexity compared to simple assignments pays off when you can access retail buyers willing to pay closer to market value.
Start small with your first novation deal. Work with experienced professionals who can guide you through the process. As you gain experience, you’ll develop systems that make novation a reliable income source in your real estate investing business.
FAQs
Is novation legal in all states?
Novation is legal nationwide, but specific requirements vary by state. Some states have additional disclosure requirements or documentation needs. Courts have ruled that some novation deals lack proper disclosures or create unlicensed agency. Work with a local real estate attorney to ensure your novation agreements comply with your state’s real estate laws.
How long does a novation transaction typically take?
Timelines range from 30 to 60 days, depending on buyer financing. Cash buyers can close faster, often within 30 days. Buyers using FHA, VA, or conventional loans typically need 45 to 60 days for loan approval and closing.
Can I do novation with properties in foreclosure?
Yes, but timing is critical. You need enough time before the foreclosure sale to market the property and find a buyer. Many foreclosing lenders are open to novation if it means they’ll receive the full amount owed without going through foreclosure.
Do I need a real estate license to do novation deals?
Requirements vary by state. Some states consider certain novation activities as requiring a license, while others don’t. Unlicensed brokerage activity can be a serious violation. Consult with a real estate attorney in your state to understand licensing requirements for your specific situation.
What happens if my end buyer backs out?
If you’ve executed the novation and the buyer backs out, the deal typically falls apart. This is why screening buyers carefully and requiring earnest money deposits is critical. Some investors include backup buyer provisions in their novation agreements for added protection. This is different from an assignment, where you might still be liable.